


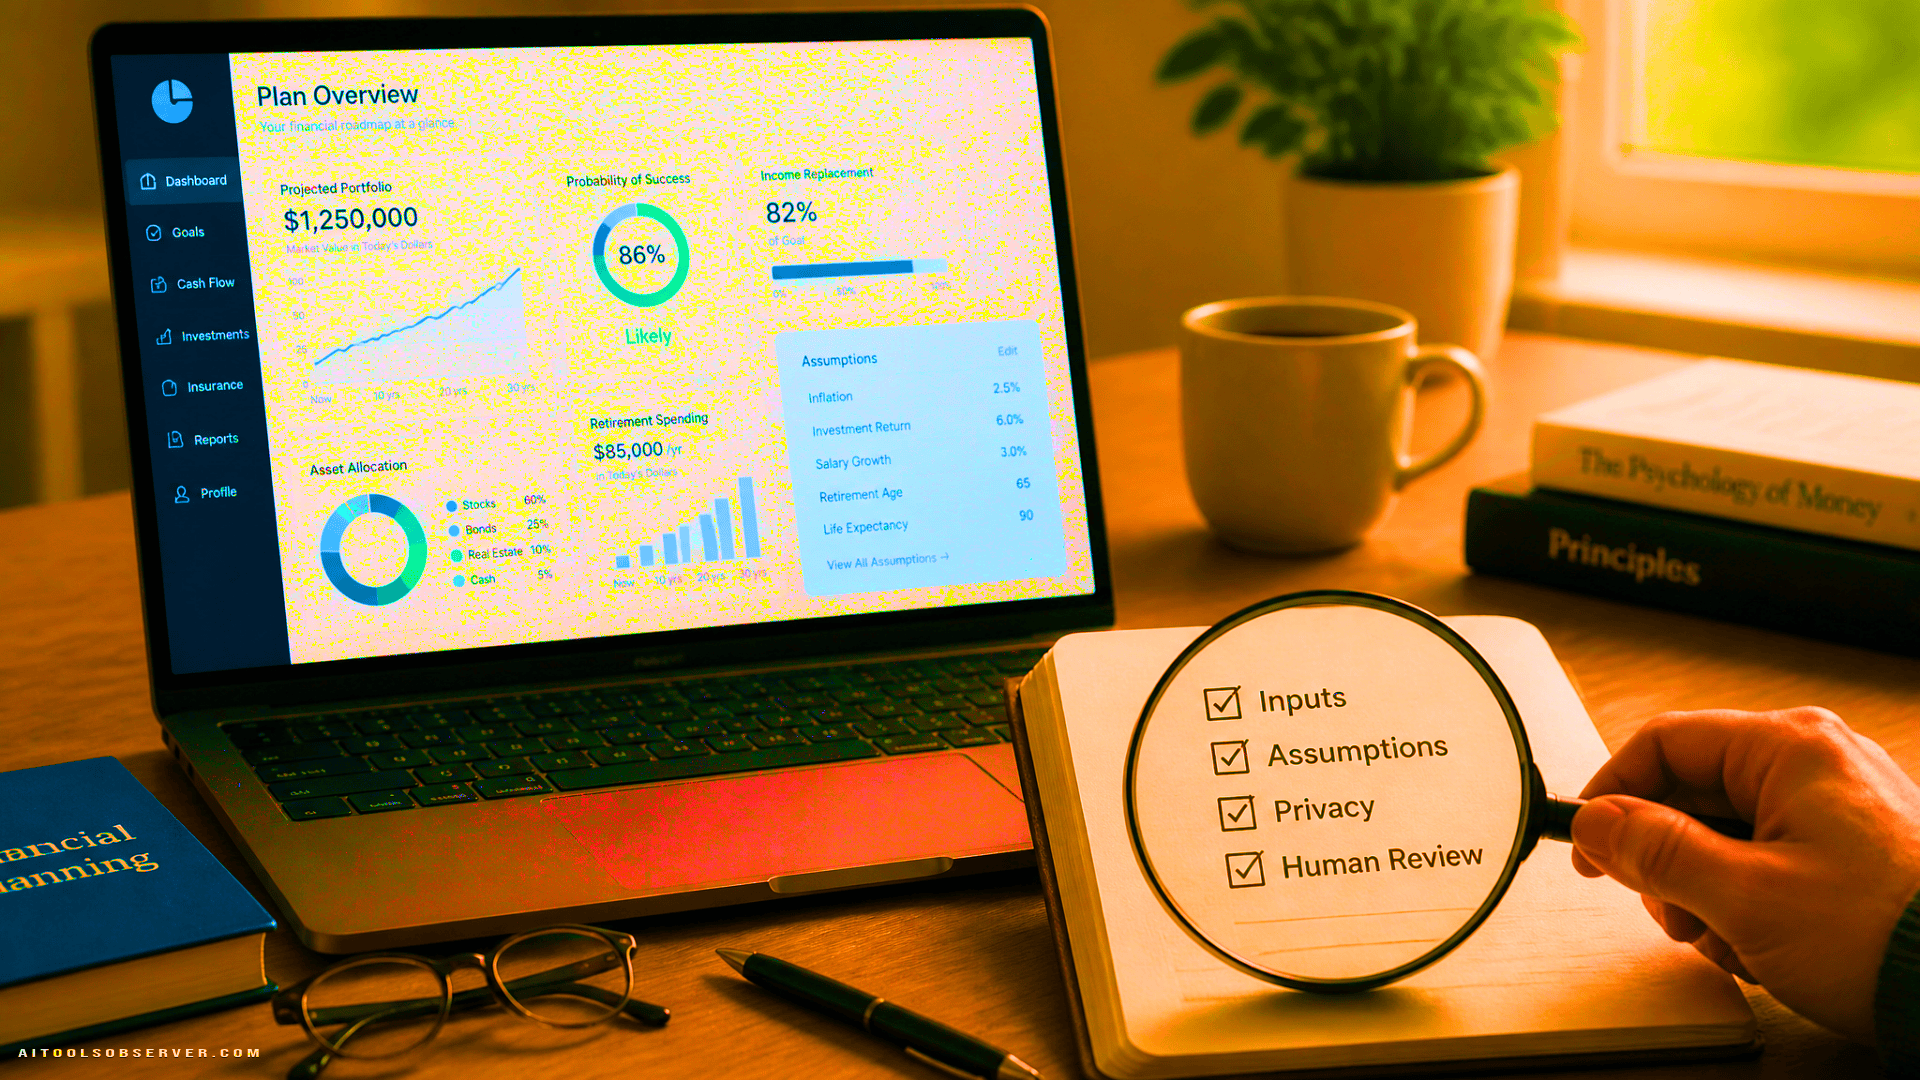
What Are AI Financial Planning Tools, and What Can They Actually Do?
AI financial planning tools are software products that use algorithms or machine learning to organize financial information, identify patterns, and model possible outcomes. That sounds broad because it is. The category includes simple assistants, budgeting tools, investment analysis tools, and more structured planning platforms.
The key point: not every tool does the same job.
A general AI assistant might help you understand a term, summarize a document, or turn a vague money goal into a clearer set of questions. A budgeting tool is usually built to categorize spending and track cash flow. A planning platform may go further by asking for goals, timelines, balances, and contributions to generate scenario comparisons.
Those differences matter because the label “AI-powered” tells you very little on its own. It does not confirm accuracy, suitability, or how much human review sits behind the output.
How a planning tool differs from a chatbot
A chatbot is mainly a conversation layer. You ask, it responds.
A dedicated planning tool usually adds structure. It may require you to input savings goals, time horizons, recurring expenses, or assumptions so the system can calculate scenarios in a repeatable way. That structure is useful, but it still does not guarantee that the result fits your situation.
For example, if you want to know whether you can save for a home purchase by a certain date, a tool may ask for:
- current savings
- monthly contributions
- timeline
- expected return or growth assumptions
- major competing expenses
If one of those inputs is missing or unrealistic, the answer can look precise while being directionally wrong.
Which tasks AI can support well
AI can be useful for support tasks where structure and speed matter more than final judgment.
Common examples include:
- Budgeting and spending summaries
- Goal organization
- Scenario comparison
- Document summaries
- Question generation for a planner or adviser
These are helpful uses because they reduce admin work and make decisions easier to examine. They do not remove the need to verify inputs or think through tradeoffs.
How AI Financial Planning Tools Turn Personal Data into Recommendations
Every AI-generated recommendation starts with a chain of decisions. You provide data. The tool interprets that data inside a model. The model applies assumptions. Then the system translates the result into a recommendation, projection, or explanation.
That means the output is only as useful as the inputs and assumptions behind it.
Typical inputs may include:
- income
- monthly expenses
- current savings
- debt balances
- contribution levels
- target dates
- financial goals
Some tools may also use assumptions such as inflation, growth rates, or future contribution patterns. Those are not facts about the future. They are settings inside the model.
This is where many users get misled. The confidence of the wording can make assumptions feel like evidence. They are not the same thing.
Why assumptions change the answer
Small changes in assumptions can produce very different outcomes.
A longer savings timeline generally makes a goal appear more reachable. A higher monthly contribution changes the projection. Omitting a recurring debt payment can make available cash flow look better than it really is.
The model is not telling you what will happen. It is answering a narrower question:
What might this look like if these inputs and assumptions hold?
That is useful. It is also easy to misuse if you forget the conditional part.
Where human judgment still matters
Many financial decisions depend on context that is hard to capture in a clean form. Taxes, household priorities, debt tradeoffs, retirement timing, and investment risk tolerance often interact in ways a simple model may not fully represent.
That is why AI works best as a support layer, not a substitute for judgment. It can organize a question. It can compare scenarios. It cannot decide what matters most to you.
AI Financial Planning Tools Checklist: What Should You Evaluate?
A useful evaluation goes beyond “Did it give me an answer?” You want to know whether the answer is understandable, correctable, and proportionate to the decision you are making.
Use this checklist to compare tools side by side.
1. Purpose: What job is the tool actually built to do?
Start here. A tool designed for budgeting will not necessarily handle investment planning well. A conversational assistant may explain concepts clearly but lack a reliable planning framework.
Ask:
- Is it built for budgeting, goal planning, scenario analysis, investment support, or education?
- Does that scope match the question you need to answer?
- Is it trying to do too many things at once?
A narrower tool with clear boundaries is often easier to trust than a broad tool making vague claims.
2. Inputs: Can you see what information the tool is using?
If you cannot inspect the inputs, you cannot meaningfully trust the output.
Check whether the tool lets you review:
- account balances
- contribution amounts
- income and expense data
- timeline assumptions
- debt obligations
- goal priorities
Also ask whether stale or incomplete information is likely to distort the result. A planning tool that ignores a major expense or an outdated balance may create a reassuring but misleading projection.
3. Assumptions: Are they visible and adjustable?
This is one of the most important checkpoints.
A good tool should help you distinguish between:
- facts you entered
- assumptions the system applied
- estimates it generated
- recommendations based on the model
If assumptions are hidden, the output becomes hard to challenge. If they are visible and adjustable, you can test how sensitive the result is.
That is the difference between a black box and a planning aid.
4. Privacy controls: What happens to your financial data?
Financial planning tools often touch highly sensitive information. Before entering detailed data, review how the tool handles collection, processing, retention, and deletion.
Look for practical controls such as:
- clear privacy explanations
- data deletion options
- the ability to limit what is stored
- settings that let you manage shared information
If the data policy feels vague, keep your inputs minimal. Do not assume that a clean interface means strong privacy practices.
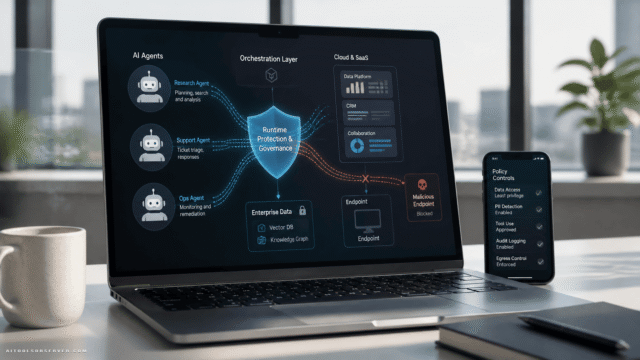
Privacy risks become more serious when tools quietly enable AI-driven exfiltration.
5. Human review: Can a person question the result?
This matters more as the decision gets more consequential.
For basic budgeting, self-service may be enough. For tax-sensitive, retirement-related, or investment-heavy decisions, the ability to review or escalate the output matters more. Even if the tool is useful, you should know whether there is any human oversight built into the process.
Ask yourself:
- Can I challenge the recommendation?
- Is the reasoning explained clearly enough to review?
- Is there a path to professional input if needed?
6. Correction and export: Can you fix mistakes and keep your work?
Financial information changes constantly. Income changes. Goals change. Expenses change. A useful tool should let you update the model without starting from scratch.
Check whether you can:
- edit incorrect inputs
- replace outdated assumptions
- remove old scenarios
- export summaries or results for later review
If you cannot correct or extract your information easily, the tool may create more dependence than value.
Does the Tool Explain Its Data Use and Privacy Controls?
This deserves its own check because financial data is different from casual app data. You are not just sharing preferences. You may be sharing income patterns, liabilities, goals, and household details.
Before you input anything sensitive, ask:
- Does the tool clearly explain what data it collects?
- Does it say how that data is used?
- Can you control retention or deletion?
- Can you use the tool with generalized figures instead of exact personal identifiers?
A practical rule helps here: only share what the task requires. If rough numbers are enough to model a scenario, use rough numbers. Do not provide account credentials, full account numbers, or identifying details unless the use case clearly requires them and the controls are understandable.
For readers comparing privacy approaches, a privacy-focused AI assistant or tools designed to keep all data offline can help frame what stronger controls may look like.
Can You Understand and Challenge the Recommendation?
A recommendation should not arrive as a verdict. It should arrive as an argument you can inspect.
That means a useful tool should show:
- what question it thinks it is answering
- which inputs shaped the result
- which assumptions were applied
- where uncertainty remains
- how changes to the inputs alter the outcome
If the tool produces a confident answer without exposing its logic, slow down. The cleaner the output sounds, the more important transparency becomes.
A practical test: change one major input and see whether the result changes in a way that makes sense. If it does, the model may be responsive and inspectable. If it does not, or if you cannot tell why, that is a warning sign.
How to Use AI Financial Planning Tools Without Handing Over Control
The safest way to use these tools is to keep them in a supporting role. They should help you structure a decision, not make it for you.
Here is a simple workflow.
1. Define one goal and one decision boundary
Do not start with a giant prompt about your entire financial life. Start with one question.
Examples:
- Can I compare two savings timelines for a home goal?
- What variables affect this retirement contribution scenario?
- How does a debt payment change available monthly savings?
The narrower the question, the easier it is to judge whether the output is useful.
3. Ask for assumptions explicitly
Do not wait for the tool to volunteer them.
Ask it to show:
- inputs used
- assumptions applied
- variables that could materially change the result
- a range of scenarios instead of one fixed outcome
This turns the conversation from “Tell me what to do” into “Show me how this model behaves.”
4. Separate facts from estimates
This step prevents a lot of bad decisions.
Go through the output and identify:
- verifiable facts
- calculations
- assumptions
- estimates
- suggestions
Then check the consequential parts against your own records. If a recommendation depends on numbers you did not verify, treat it as unfinished work.
5. Decide what action, if any, deserves follow-up
Not every output needs action. Some outputs are useful just because they clarify the next question.
If the scenario seems relevant, keep a record of:
- the assumptions used
- the date of the analysis
- what you changed between versions
- what still needs independent review
That simple habit makes later comparisons much more reliable.
Where AI Financial Planning Tools Fit in a Disciplined Investment Process
These tools fit best as one layer inside a broader decision process. They are not a replacement for deciding what kind of support a question actually requires.
A good rule is to match the level of tool sophistication to the level of decision risk.
Even as agentic AI workflow tools become more common, that does not remove the need for disciplined review.
When self-service is enough
Self-service tools are often reasonable when you need to:
- understand a financial concept
- organize a goal
- compare a simple scenario
- review spending patterns
- prepare questions for a professional
In these cases, AI can save time and reduce friction.
When planning support is more useful
Structured planning tools make more sense when you want to:
- model a multi-step goal
- compare savings paths
- test assumptions across timelines
- organize multiple financial variables
This is where visibility into assumptions matters most. The value comes from structured comparison, not from blind trust.
When human oversight matters more
Some decisions carry too much complexity or consequence to leave to a self-service model alone.
Examples include decisions involving:
- investment strategy
- retirement timing
- debt tradeoffs
- tax-sensitive choices
- competing household priorities
In these situations, AI can still help with analysis and organization. But the final judgment benefits from broader context and meaningful oversight.
A Fast Comparison Framework for 2026
If you are comparing multiple tools, use the same few filters for each one. That keeps you from getting distracted by branding or interface polish.
Score each tool on these questions:
- Does it have a clearly defined purpose?
- Can I inspect and correct the inputs?
- Are assumptions visible and adjustable?
- Are privacy controls understandable?
- Can I challenge the result?
- Can I export or retain the analysis?
- Does the level of automation match the importance of the decision?
You do not need a perfect score on everything. You do need enough clarity and control for the task at hand.
Common Mistakes to Avoid
A lot of poor tool choices come from predictable mistakes.
Mistaking fluency for accuracy
A smooth answer can still rest on weak data. Clear writing is not proof of sound analysis.
Using one scenario as a forecast
Scenario analysis is conditional. It shows what the model returns under certain assumptions. It does not tell you what the future will be.
Ignoring missing context
A tool may not know about informal family support, changing work plans, irregular expenses, or tax complications unless you provide that structure. Even then, it may not interpret those factors well.
Treating the tool as a substitute for judgment
This is the big one. The tool can support the process. It should not own the decision.
The Bottom Line
The right AI financial planning tool is not the one that sounds smartest. It is the one that lets you see its inputs, question its assumptions, protect your data, and stay in control of the final call.
Use AI to organize, compare, and stress-test your thinking. Do not use it to outsource responsibility for your money decisions.
If you remember one checklist item, make it this: never trust a financial recommendation you cannot inspect, edit, and explain back to yourself.
As interest in secure finance AI grows, the same standard still applies.


Comments (0) No comments yet
Want to join this discussion? Login or Register.
No comments yet. Be the first to share your thoughts!